Why Is USD Plunging Despite CPI Jump?
Inflation Higher Again
We’re seeing interesting price action today with the US Dollar down sharply, reversing from the initial spike higher seen in response to yesterday’s hotter-than-forecast inflation report. Headline annualised CPI for September printed 3.7% from 3.4% prior, above the 3.6% the market was looking for. Core CPI was similarly hot at 2.6% from 2.4% prior, above the 2.5% Wall Street forecast. The immediate implication is that an October hike from the Fed is still very much a possibility with pricing for a move this month jumping to above 30% from below 20% ahead of the data while pricing for a December hike is now above 90% from around 70% prior.
AI Bond Sell-Off
Despite this hawkish shift in traders’ rates expectations, though, USD is down today as focus turned to concerns over funding levels in the AI sector. In particular, alarms are sounding over the debt load being held by some big AI names as a result of the sell off we’ve seen in some AI corporate bonds leading some to question if investment in the sector has hit a wall. If see any further selling in AI bonds this could start to drag USD much lower given the link between AI spending and growth forecasts for the US. If AI bonds can stabilise, however, focus should turn back to this latest jump in inflation and hawkish Fed expectations, helping boost USD once again.
Technical Views
DXY
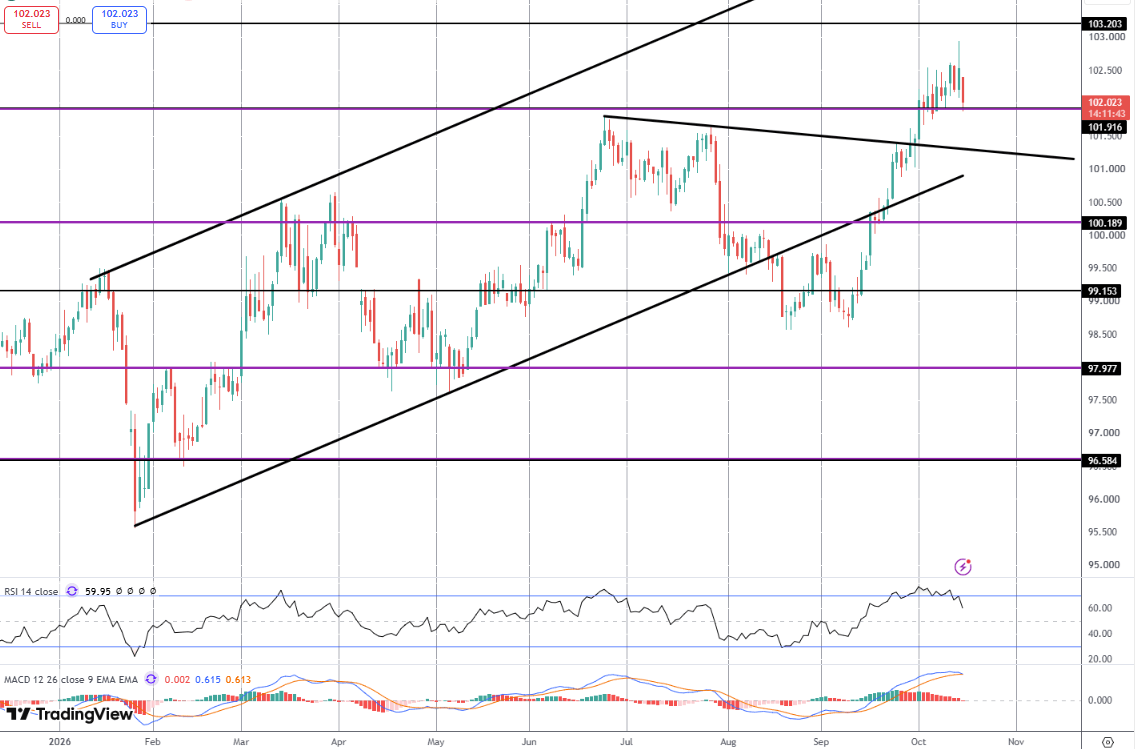
The rally in the index has stalled for now ahead of a test of the 103.20 level with price now reversing back down to retest support at 101.91. This level is holding for now and while it does, focus is on a fresh push higher. If we break below this level, a retest of trend lien support will be first focus ahead of the key 100 level.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.